Contribution record
Shows the work, knowledge, time, relationship, materials or resources offered and the task to which they belong. By itself, it creates no money, receivable or available balance.
Contribution · Entitlement · Value · Payment
In shared work, one person may bring knowledge, another time or skilled labour, another materials, and someone else money or risk. Their value cannot all be measured in the same way. A contribution record shows who brought what; an agreement determines whether an economic entitlement arises; payment shows whether that entitlement was actually fulfilled. Where economic value has been agreed, BenAkçe and BenGram are being developed as two scales within one shared record language.
Rights tracking in the application · Reference converter 0.2 open · Wallet, transfers and payments unavailableThe application’s Ben Akçe ledger tracks accepted contribution terms and manual evidence records for payments made externally. A record does not send money. The informational NBP gold and currency converter remains separate. Deposits, purchases and member-to-member value transfers are unavailable; no gold reserve, return or redemption in gold is promised.
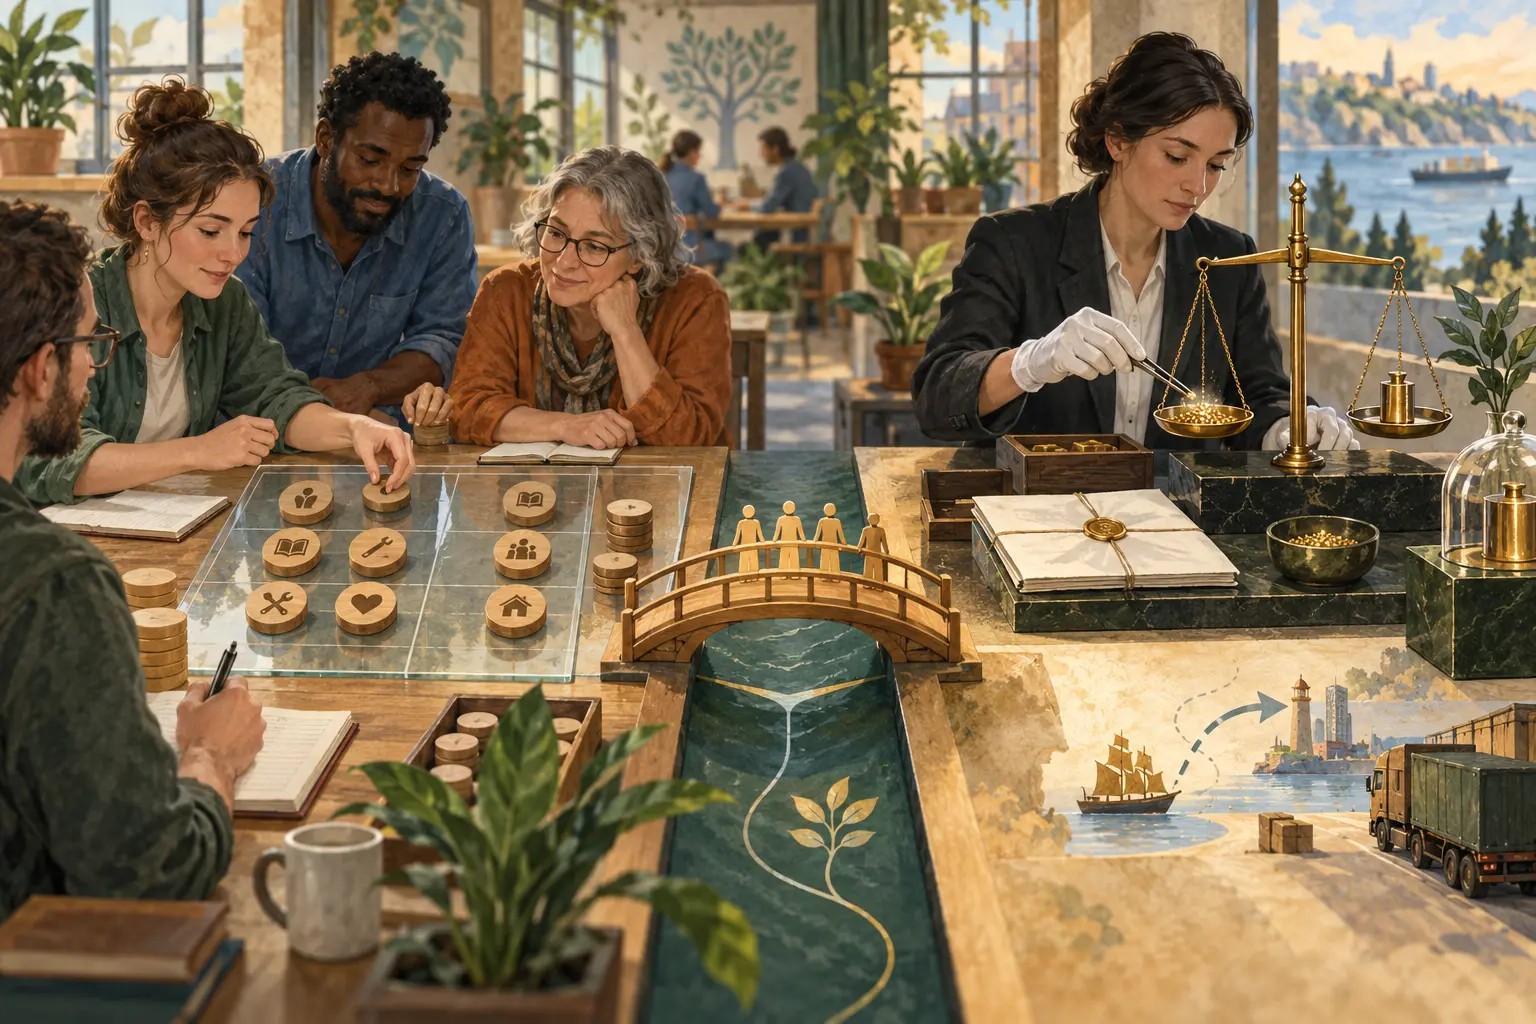
Contributions to Uşak production, education, marketplace work and other projects record the project, contribution type, agreement reference, responsible entity, funding source and payment terms separately. New project records distinguish the total contribution, prior compensation and what remains outstanding. Established payment obligations and success-dependent contributions are tracked under separate conditions. A proposed amount is not an approved right until a different authorised reviewer checks the completed work and agreed terms.
For example, an approved right of 1,000 Ben Akçe with 300 Ben Akçe actually satisfied and documented leaves 700 Ben Akçe unpaid. Contribution history and the original amount remain intact. Receipts cannot be reused; errors are corrected with an explained reversal rather than deletion. These figures are illustrative.
A payment request alone does not reduce the right or guarantee a payment date. A manual receipt is not bank or provider verification. Contribution scores do not automatically become receivables; financing, investment, ownership and revenue-share contracts remain separate. Only the member and authorised general coordination can see financial amounts.
A contribution may be offered for a fee, reimbursement of expenses, a share agreed in advance, or freely as volunteer work or a gift. Its value does not automatically create a payment; being freely given does not mean it should disappear from view. The nature of the contribution needs to be clear before work begins.
A BenBiz contribution record does not score a person’s worth. It makes visible what was brought to a particular piece of work, by whom and under which terms. Gratitude, standing within a community, an economic entitlement and actual payment are not substitutes for one another.
If Elif sews a bag, for example, her work can be recorded. If her fee and terms were agreed beforehand, acceptance of the work creates a receivable; payment is complete only when real resources have been set aside and reach her through the agreed route. The people and amounts on this page are illustrations of that distinction.
Shows the work, knowledge, time, relationship, materials or resources offered and the task to which they belong. By itself, it creates no money, receivable or available balance.
A contribution explicitly agreed as freely given. Its purpose and use remain traceable, but it does not later become a personal receivable by itself.
Compensation that arises when conditions agreed beforehand are met. Its amount, underlying work or contract, responsible party and payment date need to be clear.
Real fulfilment of an obligation through the agreed method. A record or balance on a screen does not mean funds have been paid.
Not every contribution becomes BenAkçe. Volunteer work, gratitude or a contribution score remains a contribution record unless economic compensation was agreed. Ben Akçe records the unpaid right arising from a contribution approved under previously accepted terms; it does not measure anyone’s worth or place in the community.
The proposed fixed accounting relationship is 100 BenAkçe = 1 BenGram—in other words, 1 BenAkçe = 0.01 BenGram. This is not a trading rate between two assets. It is the same reference value written at a smaller everyday scale and at a larger BenGram scale.
Project-bound amounts, conditional compensation, confirmed receivables awaiting payment, funded entitlements and completed payments need distinct states rather than one spendable-looking total.
Record
An amount expressed in BenAkçe or BenGram may be proposed, but it is not a confirmed entitlement until its conditions are met.
Entitlement
An economic right has arisen; its due date, responsible party and whether real resources are allocated remain separately visible.
Payment
An amount allocated for payment is locked against other use; it closes as paid only when real funds arrive.
These states are not a guaranteed return or an inevitable sequence. No unit measures a person’s worth; contribution points, gratitude and freely given support are not a person’s available economic entitlement.
The work is accepted and the agreed fee becomes a receivable. Once resources are allocated, any internal use would still depend on the person’s consent and a legally suitable structure.
Revenue is collected and costs, obligations and necessary provisions are accounted for. A confirmed, funded share can become available; turnover is not distributable earnings.
The repayable amount is established under the agreement and resources are set aside. An investment record alone is not a repayment or principal guarantee.
If a legally suitable system is established, an available amount could move between members. The sender’s record falls as the recipient’s rises; a transfer creates no new value.
One BenGram expresses the reference value of one gram of gold at a disclosed price source; 100 BenAkçe expresses that same value in smaller units. Conversion between BenAkçe and BenGram creates no earnings, second balance or increase in value.
A BenGram entry does not mean physical gold has been bought or held for anyone. There is no declared gold reserve, gold-redeemable balance or promise to deliver a gram of gold today. The quote type, purity, data source and pricing moment must be defined before any binding use.
Readiness for external payment is a separate state of an amount, not the meaning of BenGram. Once an entitlement is allocated for payment, the same amount must be locked against internal use; review, payment-ready and paid records must be tracked separately. Actual payment is completed in the agreed currency through an authorised route.
A contribution and its payment may happen on different days. During periods of high inflation, an unchanged number may meet fewer needs by the time it is paid. The aim is not to manufacture a return, but to explore a legible reference for discussing erosion over time.
In this design, 1 BenGram expresses the reference value of 1 gram of gold, while 100 BenAkçe expresses 1 BenGram. This gives amounts from different dates a common scale for comparison. The gold definition, purity, quote type, data source and pricing moment for any binding transaction have not yet been agreed.
A gold reference and gold backing are not the same. Gold accounting does not mean gold is held for a user; prices can fall and cannot guarantee purchasing power in every period. Actual backing could be claimed only with clear ownership, custody, costs and verifiable reserves. No such reserve is declared today.
Fixed reference ratio
100 BenAkçe = 1 BenGram1 BenAkçe = 0.01 BenGramUse a point for decimals and commas for thousands.
Currency equivalent
Daily data loads automatically; compare it with your own price if you wish.Loading the latest daily data published by NBP…
Calculated reference equivalents
The currency equivalent is derived from NBP’s latest daily gram-gold value and Table A mid rates; it is not an intraday bid or offer. The result is not a payment instruction, gold balance, proof of reserves or investment recommendation, and it excludes fees, taxes and other costs.
The tool above applies the fixed 100-to-1 accounting ratio. When it opens, it retrieves Narodowy Bank Polski’s (NBP) latest published value for one gram of 1000/1000 fine gold and its Table A mid rates for TRY, USD, EUR and GBP, then calculates the BenAkçe, BenGram and currency equivalents automatically. You can also enter a gram-gold price from another source for comparison.
This is a dated official daily reference, not a live intraday bid or offer. The currency equivalent is derived by dividing NBP’s gram-gold value in PLN by the mid rate for the selected currency. The source used for binding payments will be decided separately; this calculation is not a binding quote, payment amount or guarantee that value will be preserved.
Revisit the homepage’s shared-production example through contribution, entitlement and payment. People, transactions and amounts are illustrative, not an open project or an income promise.
Suppose Elif has a confirmed receivable of 250 BenAkçe. That is another way of writing a reference value of 2.50 BenGram. If resources for only 50 BenAkçe have been allocated for external payment, 200 BenAkçe remain awaiting payment while 50 BenAkçe are marked payment-ready. Unit and payment state remain distinct; her total entitlement does not become 300 BenAkçe.
Deniz funds materials. Investment terms and risks are recorded; money in use by the project is not also shown as an available balance.
Her fee and payment date are agreed beforehand. Once the work is accepted, her receivable is confirmed. Waiting for an investor to earn a profit is not an automatic condition.
In this example, a share of a defined distributable result is agreed. Her contribution is recorded immediately, but unrealised outcomes are not shown as confirmed earnings.
The event that creates his sales-linked entitlement is agreed in advance. Orders, collection and any refunds are tracked separately.
The donation belongs to its designated purpose, not to the supporter’s withdrawable account. Its use must respect the donation’s conditions.
Suppose resources for only 50 BenAkçe have been allocated for external payment. The remaining receivable and payment obligation continue.
After payment: 200 BenAkçe in outstanding receivables plus a completed payment record for the currency equivalent of 50 BenAkçe. The paid amount is no longer an active balance.
BenAkçe and BenGram are two ways of writing the same reference here; states such as awaiting payment or paid remain separate from the unit. The numbers are illustrative and do not set a rate of return.
Revenue and distributable value are distinguished. Resources are allocated to confirmed rights; available balances and the payment-ready portion are shown separately.
Expected receipts are not ready money. Previously confirmed fees remain visible; delays are not hidden by changing a record’s name.
Conditional earnings may not arise and investments may lose value. Confirmed debts do not automatically disappear. A shortfall cannot be filled by recording new BenAkçe; rights remain subject to applicable law and agreements.
Each transaction needs its actual amount, currency and date, plus any gold reference and price source. The reference must be clearly identified as informational or as an agreed term that affects the payment calculation.
Resources held pending use are different from resources committed to production. If a donation buys fabric, it has become fabric; the same gold cannot still be shown as held in reserve. Project funding cannot simultaneously back another available balance.
Any gold-denominated payment obligation needs rules for who bears gold-price increases, how backing is maintained and when the conversion price is fixed for a lira payment. Equal nominal reference units do not give an investment record and an available balance the same risk or liquidity.
The converter on this page performs a calculation; it does not accept deposits, sell BenAkçe, create an account or balance, transfer value between members or initiate a payout. Early record trials should likewise test workflows and appeal routes without moving real money. Financial functions must not open before specialist review and the necessary authorised arrangements are in place.
The BenBiz Store’s actual sales and payment route will be set up separately once the responsible commercial entity and an appropriately licensed payment partner have been selected. Domestic payments may then support TRY and approved foreign currencies, while international availability will depend on the provider’s supported countries and currencies. No provider has been selected and sales have not begun. Acquiring BenAkçe or BenGram will not be a prerequisite for shopping at the Store.
Calling something points or members-only does not determine its legal character. Payment, electronic-money, investment and donation activities require separate assessment with legal, accounting and appropriately authorised specialists.
Every record needs an owner, the work or agreement behind it, a responsible party, conditions and a due date. Who may assess, correct or hear an appeal must also be clear.
Although the ratio of 100 BenAkçe to 1 BenGram is fixed, the gram-gold purity, quote type, source, time, costs and effect on a payment calculation must be disclosed. A reserve that does not exist must not be represented as available.
The same value must not be used twice. Reinvestment removes funds from the available balance; the source and associated risks remain traceable.
Necessary permissions, authorised-provider arrangements, accounting, tax, data security and responsibility for actual payments must be resolved before launch.
First step: a conversation
If you work in economics, law, accounting, software or community practice, you can share your questions and the gaps you see. This is not an invitation to invest; it is an invitation to test a model that keeps contributions visible, entitlements clear and payments safe.
I want to contribute my knowledgeYour email app opens; you choose whether to send the message. Sending it does not mean publication or acceptance. Do not send passwords, payment details or confidential documents.